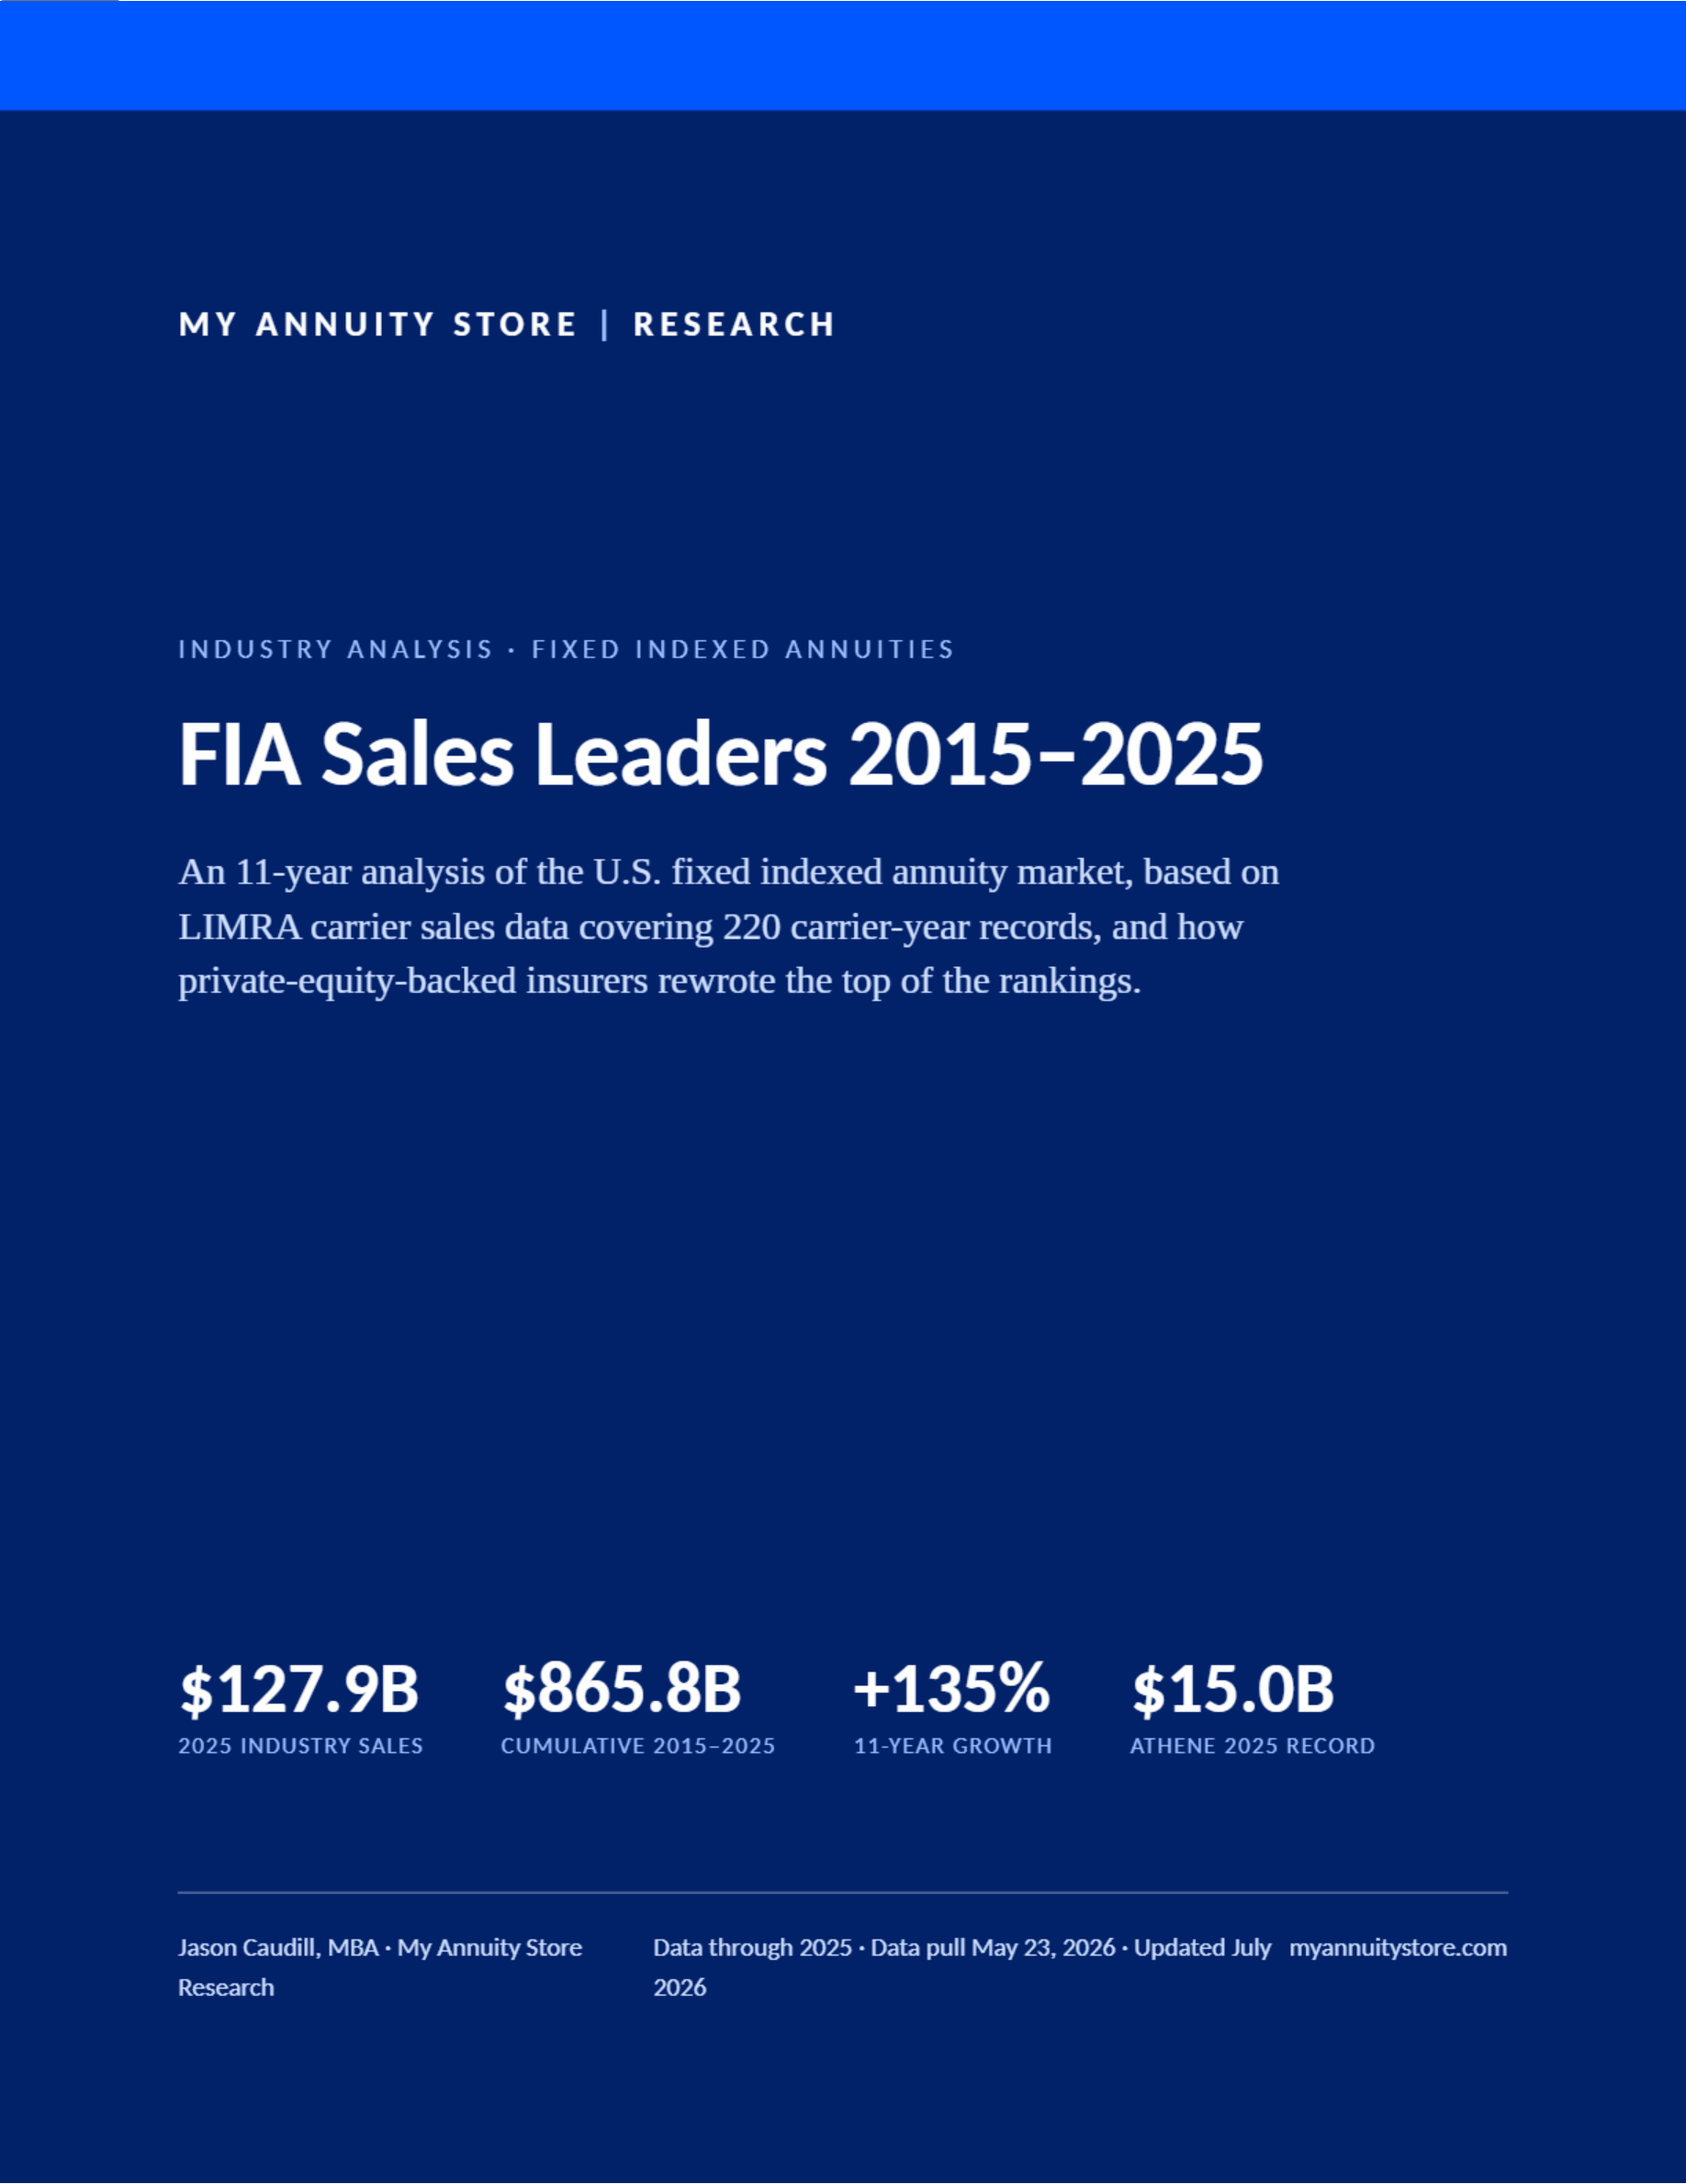
The headline numbers look modest. U.S. industry FIA sales grew from $54.5 billion in 2015 to $127.9 billion in 2025, a 135% increase. One level down the picture changes. Athene’s annual FIA sales went from $2.4 billion to $15.0 billion, roughly six-fold, in a window where the market only doubled. Allianz held an $8.7 billion to $10.2 billion range for five years, fell to $5.0 billion in the pandemic-disrupted 2020 cycle, and has finished second every year since except 2023.
What happened in between is a story about who owns these companies. Apollo Global Management spent the better part of a decade rebuilding Athene’s balance sheet around alternative credit and used the resulting yield advantage to win FIA business one independent distribution channel at a time. By 2025, three of the top five FIA carriers were affiliated with private equity or alternative asset managers.
The Top 20 have held about 85% of the market for the entire decade. That concentration has been remarkably stable even as the cast at the top changed dramatically. The dip came in 2020, when sales fell to $55.5 billion. The surge came in 2024, when sales jumped 32% in a single year as the Fed’s rate cycle made FIA crediting competitive against bonds and CDs for the first time in over a decade.