The Annuity Buyer’s Guide (2026)

HomeResearchThe Annuity Buyer’s Guide (2026)
BUYER'S GUIDE · 2026 EDITION · 43 PAGES

An annuity is a long-term contract, and the difference between the right one and the wrong one is almost always in the details. This guide explains those details in plain English, from the four product types to the 12 questions every buyer should ask before signing.

Published by My Annuity Store, Inc. Its structure is adapted from the NAIC’s consumer guidance for deferred annuity buyers, with original commentary. Thirteen chapters, a side-by-side product table, and a printable checklist. Educational use only.
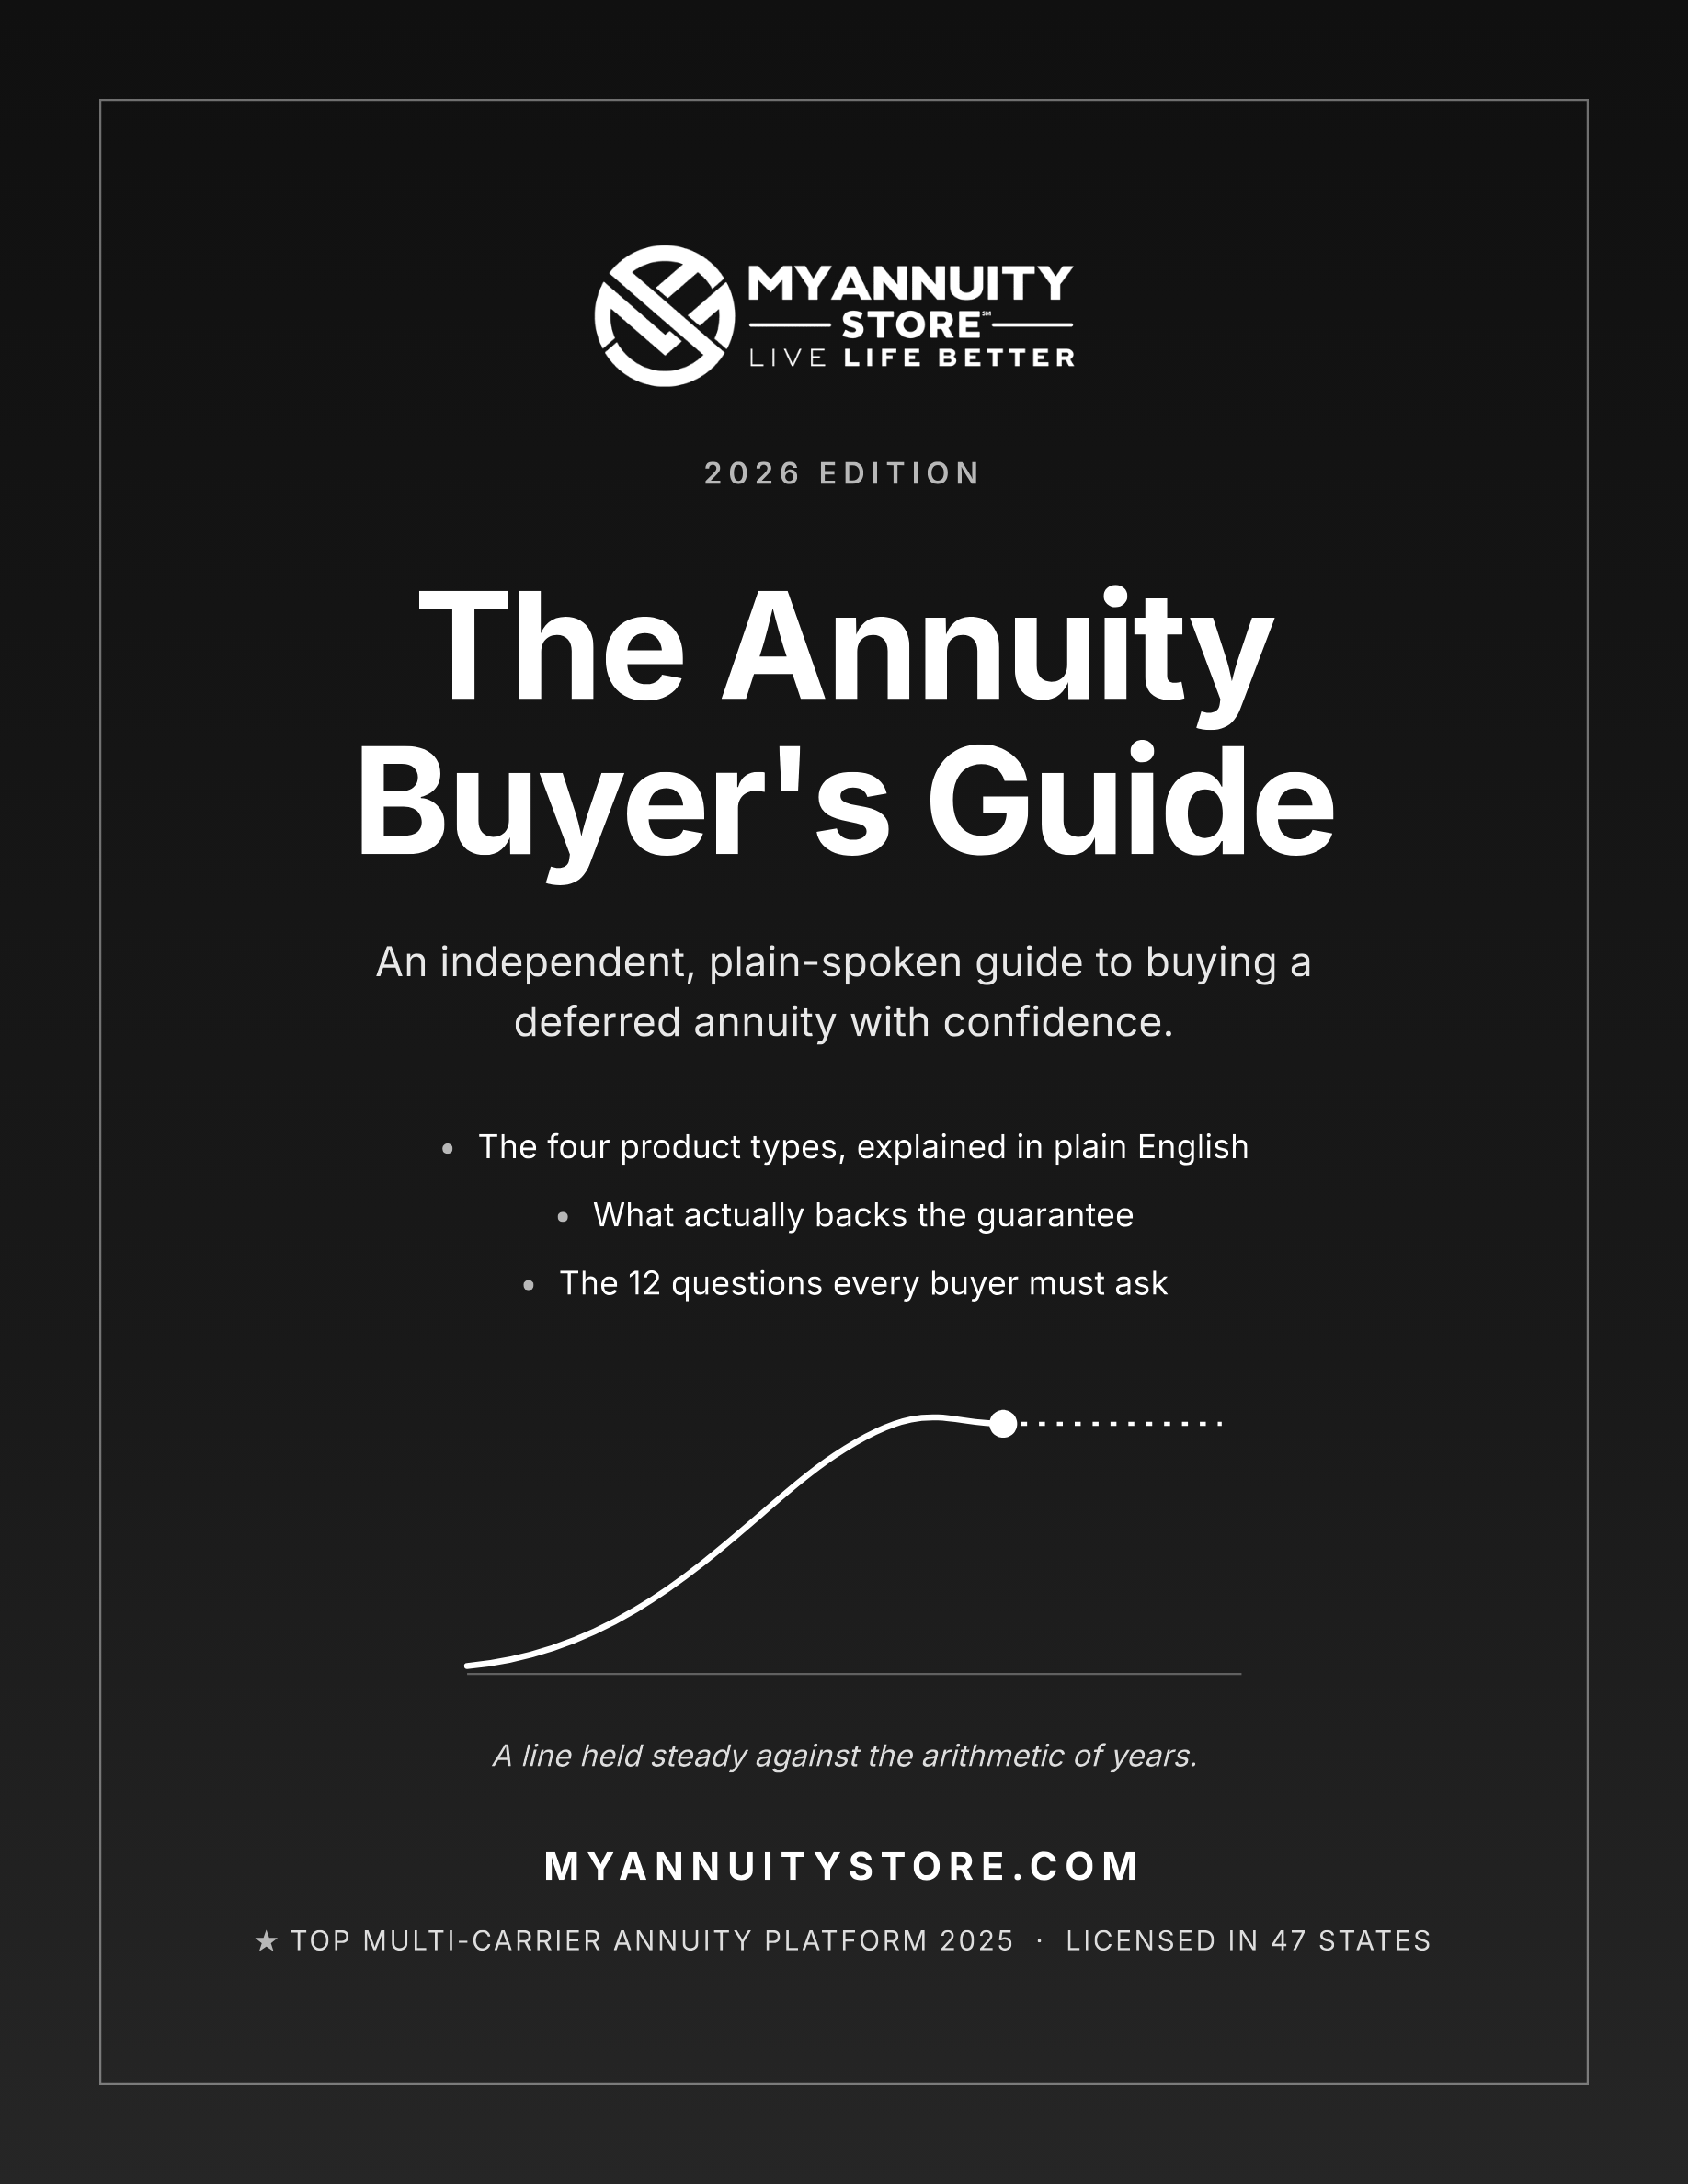
Cover of The Annuity Buyer's Guide, 2026 edition
THE GUIDE IN FOUR NUMBERS
0
ANNUITY TYPES EXPLAINED
0
QUESTIONS TO ASK BEFORE YOU SIGN
$
0
K
TYPICAL STATE GUARANTY LIMIT PER INSURER
0
STATES WITH THE NAIC BEST INTEREST RULE

Sources: NOLHGA; NAIC (48 states as of February 2025). Full citations below.

CHAPTERS 1 THROUGH 6

FOUR PRODUCTS, FOUR LEVELS OF RISK

Every deferred annuity trades off three things: how your money grows, when you can reach it, and what is guaranteed. A fixed annuity or MYGA locks a rate for a set term, much like a CD with tax deferral. A fixed indexed annuity credits interest based on a market index with a 0% floor, while caps and participation rates limit the upside.

A registered index-linked annuity (RILA) offers more upside with only partial protection, so a bad year can cost principal. A variable annuity puts you fully in the market through subaccounts, with layered fees and no floor unless you buy a rider. The guide includes a side-by-side table of all four.

It also covers the three documents you must read (contract, disclosure, and illustration), how surrender periods and premium bonuses work, and the most common costly mistake: a surrender period longer than your real time horizon.

CHAPTER 2

WHAT BACKS THE GUARANTEE

Every annuity guarantee, including “principal protection,” is a promise from the insurance company, backed by its claims-paying ability. Annuities are not bank deposits, are not FDIC insured, and are not guaranteed by any federal agency.

If an insurer fails, the state guaranty association where you live is the backstop. Most states cover at least $250,000 in annuity value per owner, per insurer. Connecticut, New York, and Washington cover $500,000, and California covers 80% of the value up to $250,000.

That is why the carrier’s financial strength rating is the first thing to check, and why very large purchases are often split across more than one carrier.

CHAPTERS 7 THROUGH 10

RIDERS, TAXES, AND YOUR RIGHTS

Long-term care riders can help, but they are not long-term care insurance. Withdrawals from a nonqualified annuity come out as earnings first and are taxed as ordinary income, with a 10% additional tax before age 59½ in most cases. Beneficiaries get no step-up in basis on annuity gains.

In 48 states, agents must follow the NAIC best interest standard when recommending an annuity. If you ask, the agent must give you a written estimate of the commission from the sale.

You also get a free look period, generally 10 to 30 days depending on the state, to return the contract. The guide explains what to check during that window and what you may give up when replacing an existing annuity.

CHAPTER 11

THE 12 QUESTIONS EVERY BUYER MUST ASK

If the agent cannot answer all twelve clearly and in writing, you are not ready to sign.

  1. What type of annuity is this, and why is it right for me?
  2. How long is the surrender period, and what is the charge schedule by year?
  3. What is guaranteed, and what is not?
  4. What is the minimum interest rate guaranteed?
  5. What will I pay each year in fees, charges, and adjustments?
  6. How much can I withdraw each year without a charge?
  1. What are my income options at the end of the term?
  2. If I die before taking income, what do my beneficiaries receive?
  3. How is this annuity taxed for me and for my beneficiaries?
  4. What commission or compensation are you receiving?
  5. Have you compared this to products from at least three other carriers?
  6. What is my free look period in this state, and how do I return the contract?

“THE RIGHT PRODUCT WILL STILL BE AVAILABLE NEXT WEEK.”


– From Chapter 10, on pressure to sign

REFERENCES

SOURCES

This guide is educational and does not constitute legal, tax, or investment advice. Annuities are not FDIC insured, are not bank deposits, and are not guaranteed by any federal agency. All guarantees are based on the claims-paying ability of the issuing insurance company. Guaranty association limits vary by state.

  1. NAIC, Buyer’s Guide for Deferred Annuities.
  2. NAIC, Annuity Suitability and Best Interest Standard (Model Regulation #275). 48 states as of February 2025.
  3. Nassau Financial Group, Model Reg #275 Disclosure FAQ.
  4. NOLHGA, How You’re Protected.
  5. Connecticut Life and Health Insurance Guaranty Association, FAQ.
  6. FINRA, Annuities.
  7. IRS, Publication 575 (2025), Pension and Annuity Income.
  8. IRS, Revenue Ruling 2005-30.
  9. LIMRA, Final U.S. Retail Annuity Sales, 2025. March 23, 2026.

Copyright 2026 My Annuity Store, Inc.

READ THE FULL GUIDE

Forty-three pages, thirteen chapters, nine sources. Free, no email required.